The road to $10 billion: Mongolia's stock market queues its next leg of growth
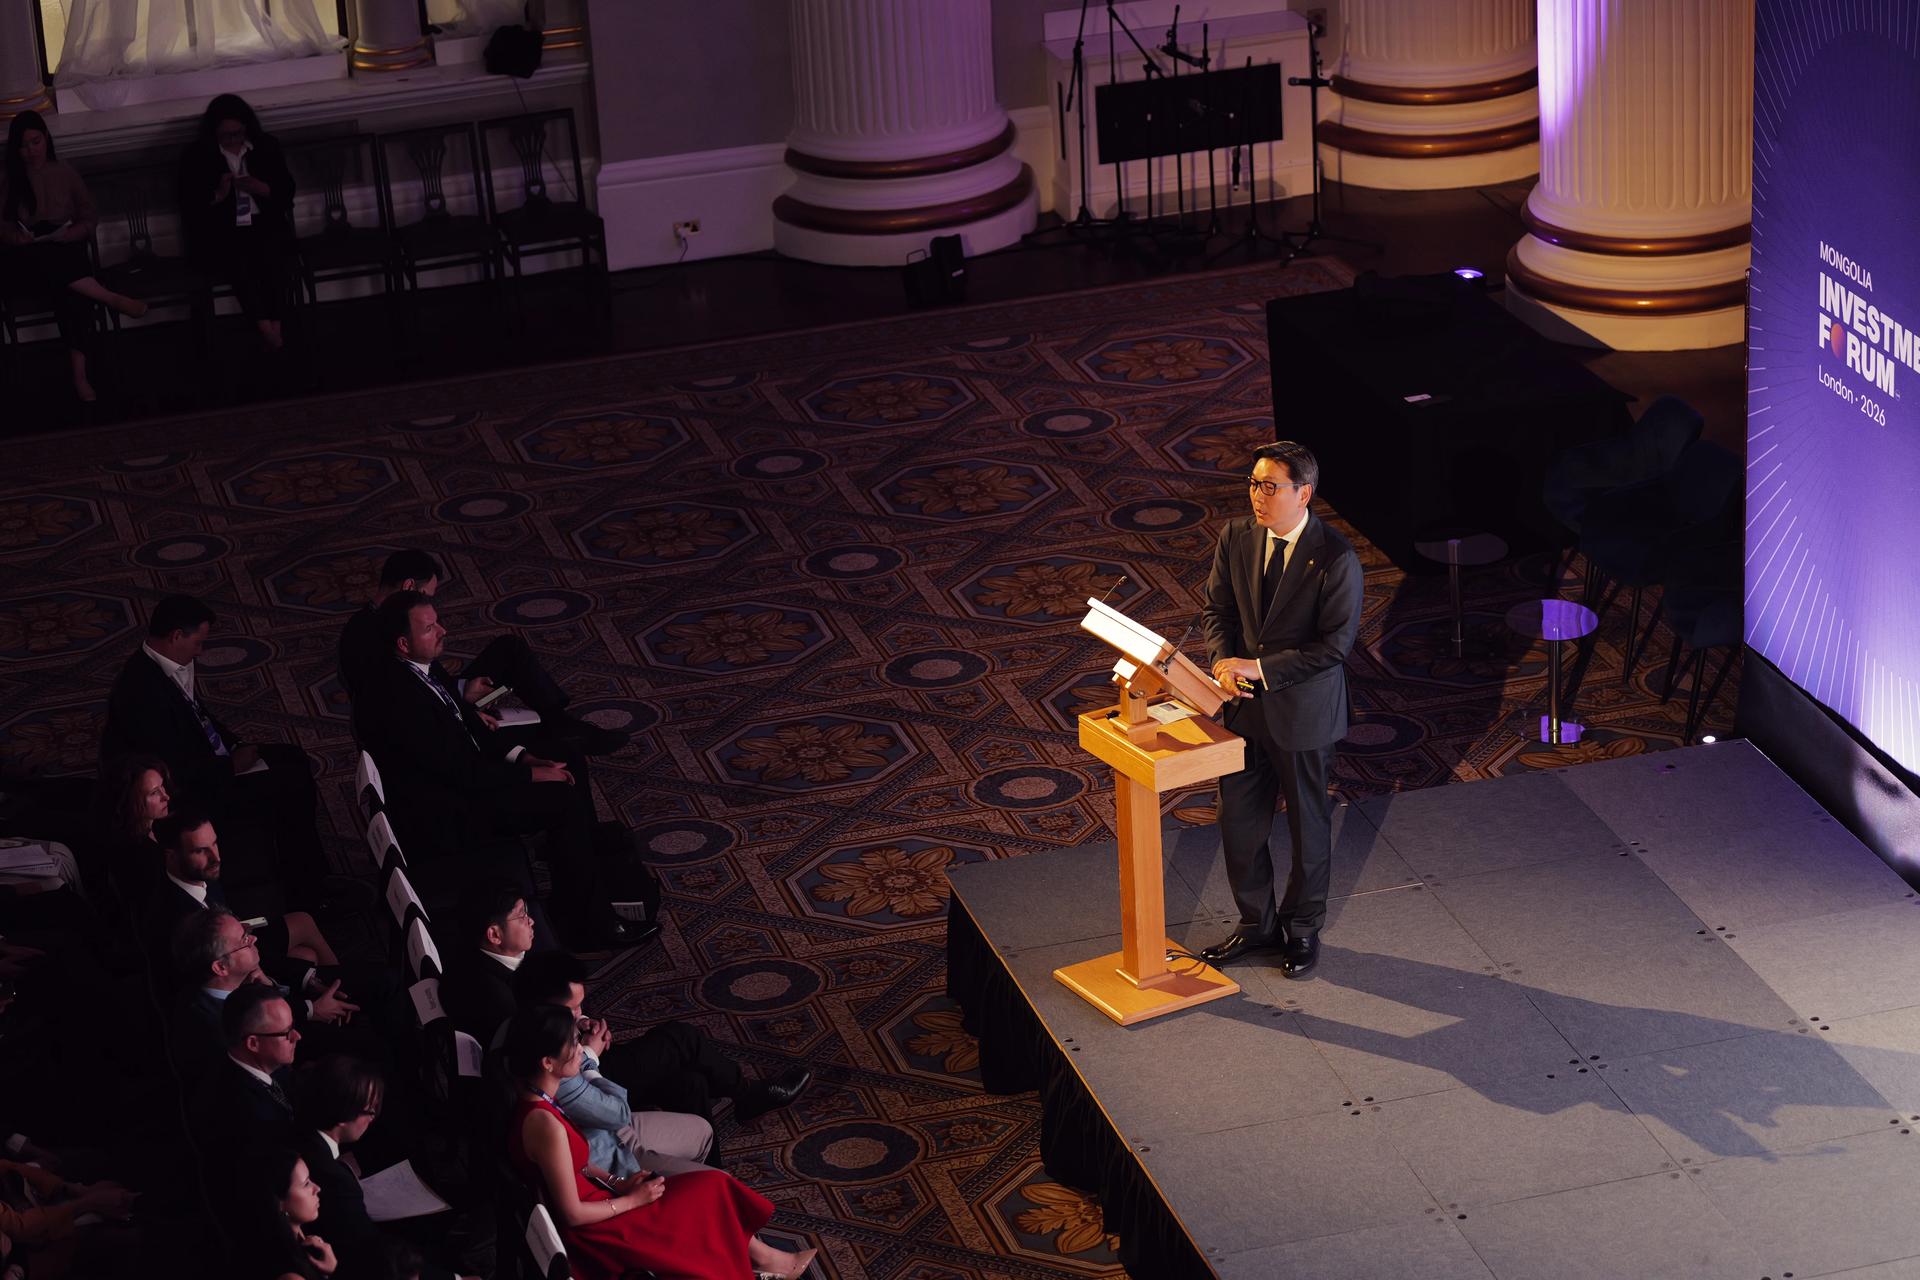
At the Mongolia Investment Forum, held at Mansion House on 15 September, the Mongolian Stock Exchange (MSE) set out a path from a market capitalisation of $4.4 billion today to $10 billion by 2028. What makes the figure worth examining is that most of the increment is already named.
To support this ambitious strategy, Munkhbat D., CEO of the Mongolian Stock Exchange, announced at the forum the launch of "Mongolian Capital Market 2.0: Roadmap for Technology, Infrastructure and Dual Listings"—a strategic joint programme with the London Stock Exchange Group (LSEG) and the Mongolian Central Securities Depository (MCSD). The roadmap focuses on modernizing market infrastructure and easing the path for domestic firms to execute international dual listings.
A decade of compound growth
The growth so far has been rapid. Market capitalisation has risen four-fold since 2020 and at a compound annual rate of nearly 18% over the past decade, while the benchmark TOP-20 index gained close to 30% in the past year alone. Yet the market remains small relative to the economy, at around 17% of GDP. That gap is precisely what the exchange proposes to close, and it has broken the task into three tranches.
Three sources of new supply
The first is further follow-on public offerings by the systemically important banks (SIBs) on an international exchange. Under a 2021 amendment to the Banking Law, Mongolia's five systemically important banks were required to list, and their initial offerings between 2022 and 2023 drew more than 70,000 investors. Follow-on offerings from SIBs banks along with some blue-chip companies are expected to add $1.3 billion in market capitalization, expanding the free float of the institutions that anchor the exchange.
The second and largest tranche is the privatisation of state-owned enterprises, which could contribute $2.4 billion. Selected assets across mining, energy, finance and transport are being restructured under a National Privatisation Fund for listing at home and, in time, abroad. Much of the programme's credibility rests on the company it keeps. Franklin Templeton signed on in June as the government's first outside partner, and BlackRock, the world's largest asset manager with $15.3 trillion under management, has since followed.
The choice of partners is not merely reputational, because both firms have a track record in exactly this kind of transaction. Franklin Templeton, with more than 75 years of history and operations in more than 30 countries, has managed comparable state portfolios in Romania, through Fondul Proprietatea, and in Uzbekistan. The Uzbek fund is the more recent proof, and a completed one: a portfolio of 13 strategic minority stakes of 25% to 40% in major state enterprises, which Franklin Templeton dual-listed on the London and Tashkent exchanges in May 2026, the first international equity listing in Uzbekistan's history. The offering raised $692 million and drew order books of roughly $2.9 billion, more than four times the stock on offer. It was anchored by cornerstone investors including BlackRock, ranked as the largest London listing since 2021 and, at home, exceeded every previous Uzbek IPO combined.
BlackRock's contribution is of a different kind: its Financial Markets Advisory arm builds institutional capacity for governments rather than managing their money, and has advised sovereign funds and central banks in some 40 countries. For Mongolia, that experience is the reassurance. The privatisation tranche is the biggest part of the plan and the one Mongolia has least experience delivering, and it is now backed by managers who have carried comparable state assets to market elsewhere.
The third tranche, worth a further $2.3 billion, turns on strategic assets and dual listings, of which Erdenes Tavantolgoi is the centrepiece. The company sits on 8.1 billion tonnes of coking coal and already supplies close to 30% of China's consumption. Secondary trading of its shares on the MSE is scheduled to begin in the fourth quarter of 2026, with an international dual listing to follow.
The conditions in its favour
Three developments make the sequence more than a wish list. Mongolia retains FTSE Russell frontier classification, and in 2025 Khan Bank became the first Mongolian company admitted to the corresponding index, a step that index-tracking funds tend to follow. Foreign and domestic investors are treated alike, with no restriction on repatriating capital. The tax regime has also moved in investors' favour: capital gains tax on listed securities would be reduced by between 50% and 90% until 2040, alongside a halving of tax on dividend and interest income.
Opportunity and execution risk
None of this is guaranteed. Reaching that target depends on execution, on demand keeping pace with the many new shares coming to market, and on commodity cycles that Mongolia does not control. Even so, the distinction worth drawing is between markets that hope to grow and markets that have queued the instruments to do so. On the evidence presented in London, Mongolia belongs to the second group. For investors weighing an allocation, the early-mover question is no longer whether new listings will come, but at what price they wish to buy in.
The full pitch deck and further information on Golomt Bank are available on the CMM platform: https://capitalmarkets.mn/directory/mongolian-stock-exchange.